How Australians Can Buy a Holiday Home in Queenstown (2026 Guide)
Thinking about a holiday home in Queenstown? Australian citizens can buy in NZ without government approval, and there's no stamp duty. The trick is the finance. Luckily, we do this all the time for clients on both sides of the Tasman.

By Chris Dodson, Director and Principal, Mortgages Plus. Last updated: 29 September 2026
Queenstown is a three-hour flight from Sydney, Melbourne or Brisbane. It offers world-class skiing in winter, lakes and hiking in summer, and a property market that has held its value. It's no surprise that more Australians are asking whether they can own a piece of it.
As a Kiwi-born mortgage broker based in Manly, I help clients with property finance on both sides of the Tasman, from Kiwis buying in Australia to Australians purchasing property in New Zealand. Queenstown comes up more than anywhere else. It's also a place I know well, having spent plenty of weekends there while studying at the University of Otago. For Australian citizens, buying there can be more achievable than many people realise.
This guide explains how Australians are funding Queenstown purchases in 2026, what to expect from NZ lenders, and the rules to know before you rent the property out.
Can Australians buy property in Queenstown?
Yes. New Zealand banned most overseas buyers from purchasing existing homes in 2018, but Australian citizens are exempt. According to Land Information New Zealand, Australian citizens can buy land classed as "residential" or "lifestyle" without consent from the Overseas Investment Office.
A few details matter:
- Australian citizens are exempt whether or not they live in NZ.
- Australian permanent residents (who aren't citizens) are only exempt if they're ordinarily resident in NZ. If you're a PR living in Australia, you'd normally need consent.
- Some land classed as "sensitive" (for example, very large rural blocks or land beside lakes and reserves) has extra rules. Your NZ lawyer will check this before you sign.
Queenstown vs an Australian holiday home: key differences
Buying in Queenstown is surprisingly similar to buying a holiday home in Australia in some ways, and very different in others. The two biggest differences work in opposite directions: you'll save on stamp duty, but you'll need a much bigger deposit.

The takeaway? Queenstown can cost less upfront than you'd expect, thanks to no stamp duty, but the finance takes more planning. Because NZ banks want a 30% to 40% deposit from Australians, most buyers fund it by releasing equity from their Australian home.
What does a Queenstown property cost?
Queenstown-Lakes is one of New Zealand's most expensive property markets. The average property value was about NZ$1.96 million in August 2026, up around 6.9% over 12 months (Opes Partners, REINZ data). Large trophy homes push that average up, and you can still find a nice home for around NZ$1 million.
Apartments and townhouses in areas like Frankton, Lake Hayes Estate and Jack's Point are more affordable than lakefront homes in Queenstown Hill or Kelvin Heights, which can run well into the multi-millions. Wānaka, about an hour's drive from Queenstown Airport, is another popular option.
One cost you won't pay: New Zealand has no stamp duty. Your upfront costs are mainly legal fees, a building inspection and any valuation, which can save you tens of thousands compared with buying in Australia.
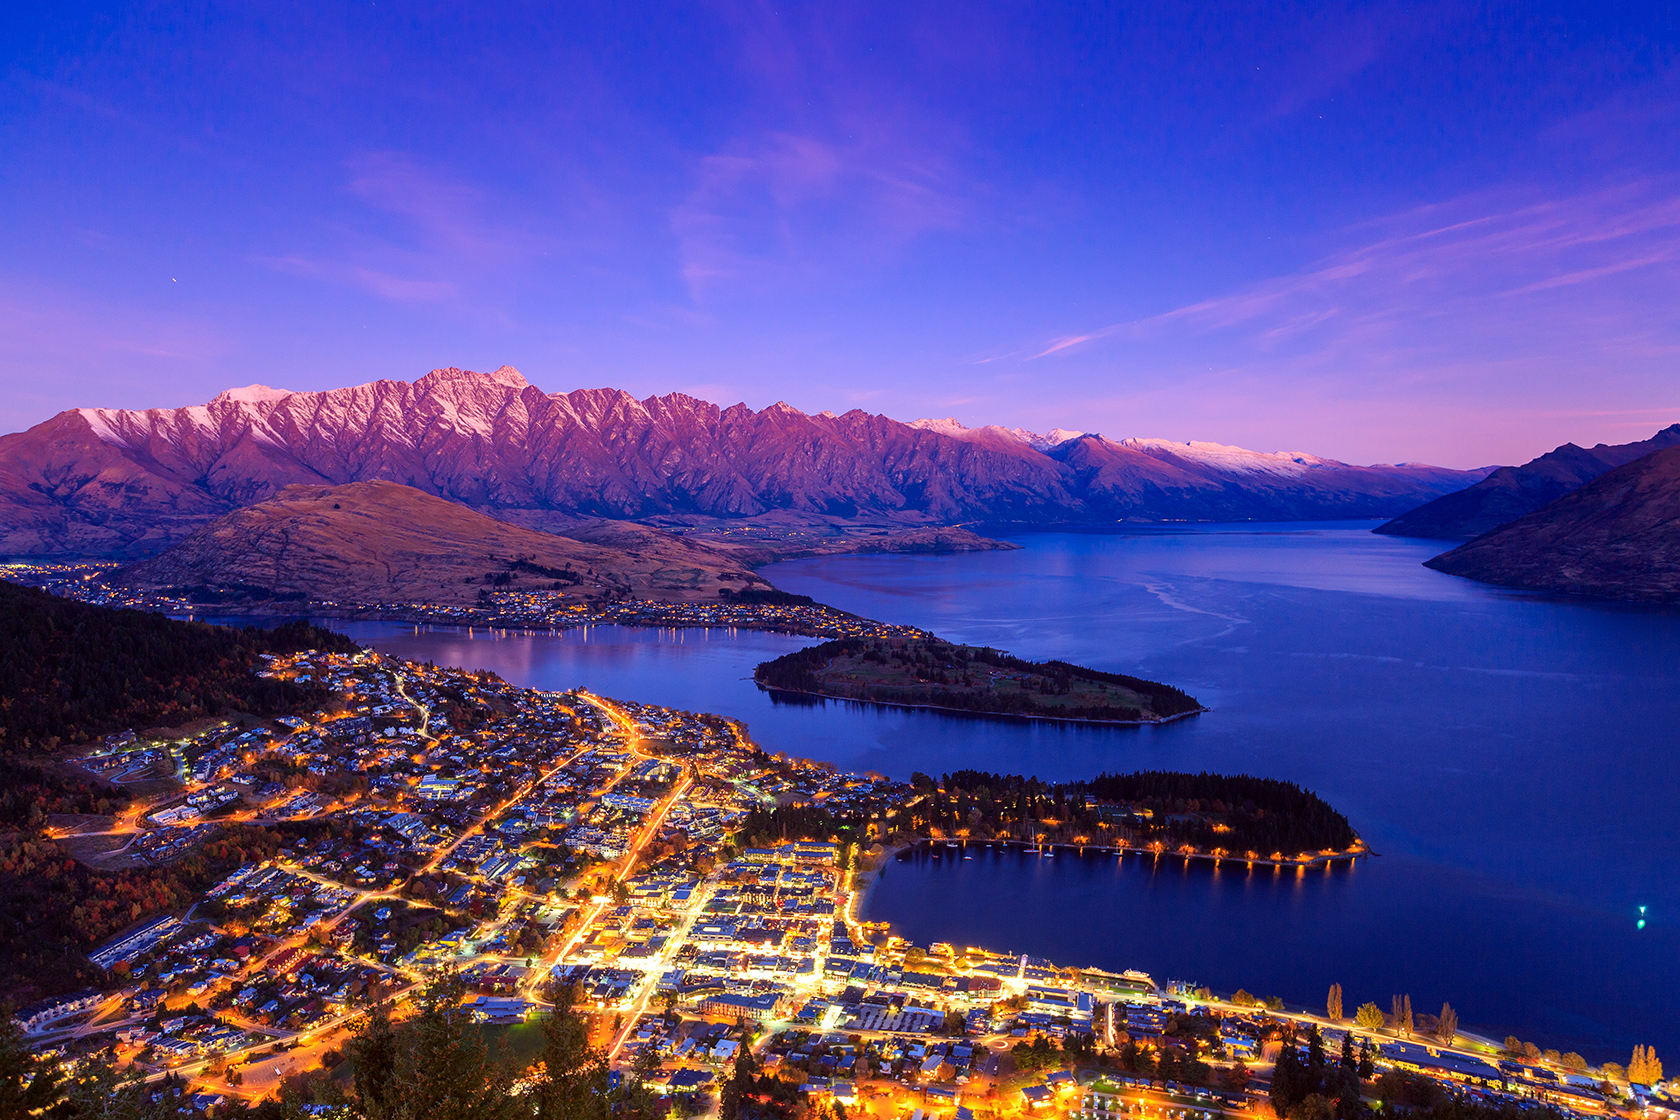
Queenstown | With its towering mountains and lakeside location, Queenstown is a hub of adventure bursting with adrenaline and fun. Source: www.newzealand.com/us/queenstown
How much deposit do you need?
This is where most Australians get caught out. NZ banks treat borrowers who live and earn overseas as higher risk.
As a guide:
- Most NZ banks lend 60% to 70% of the property value to non-residents, so plan on a 30% to 40% deposit
- Your Australian income will be assessed in NZ dollars, often with a buffer for currency movements
- NZ low-deposit and first home schemes don't apply to non-residents
- On a NZ$1.5 million apartment, that means a deposit of roughly NZ$450,000 to NZ$600,000, plus costs.
Using equity in your Australian home to fund the deposit
Most Australians don't have $500,000 sitting in a savings account. But homeowners who have owned property for several years may have substantial equity available in their Australian home. You can potentially release that equity to help fund the deposit and purchase costs in New Zealand.
Here's how it works:
- Release equity from your Australian property. An Australian lender increases your existing loan (or sets up a separate split) against your Australian home, and the funds become your deposit.
- Transfer the funds to NZ. You move the money across using a bank or specialist foreign exchange provider.
- Take out an NZ mortgage for the balance. An NZ lender funds the rest of the purchase, secured by the Queenstown property.
Not every Australian lender takes the same approach to releasing equity for an overseas property purchase. Policies also differ on how much equity can be released and how the proposed NZ loan is treated when assessing borrowing capacity. Getting the structure right before applying can help avoid unnecessary applications, delays or even declines.
Example
A Sydney couple own a home worth A$2.2 million with an A$600,000 loan. They want a NZ$1.5 million apartment in Frankton.
- They release equity from their Sydney home to cover the deposit and costs
- An NZ lender funds 60% to 70% of the purchase price
- Their Sydney home isn't used as security for the NZ loan, which keeps the two properties separate
This example is for illustration only. Your borrowing capacity depends on your income, expenses and lender policy.
The mistakes I see Australian buyers make
Having worked with clients on both sides of the Tasman, these are the issues I see most often:
- Falling in love with a property before sorting finance. Queenstown's best properties move quickly. Buyers who haven't organised their Australian equity release and NZ pre-approval often miss out, or sign unconditionally and scramble to settle.
- Assuming an Australian bank will lend on the NZ property. Most won't. The finance usually needs two lenders, one in each country, and the order you apply in matters.
- Underestimating the deposit. Buyers used to 10% or 20% deposits in Australia are often surprised that NZ banks want 30% to 40% from non-residents.
- Ignoring the rental rules. If you're counting on short-stay income to help cover costs, check the zoning and council rules first. Not every property can be let on Airbnb without consent.
- Leaving currency to the last minute. A small movement in the exchange rate on a six-figure transfer can cost thousands. Plan your transfer, and consider locking in a rate.
The common thread is timing. Get the structure right before you start making offers, and the purchase will be much smoother.
Managing currency risk
Because your deposit moves from AUD to NZD, the exchange rate on the day you transfer affects how far your money goes. A few tips:
- Compare specialist FX providers with your bank. The difference on a large transfer can be thousands of dollars.
- Ask about forward contracts, which let you lock in a rate for a future settlement date.
- If you plan to repay the NZ loan from Australian income, remember that currency moves will change your repayments in AUD terms.
Renting it out: Queenstown's short-stay rules
Many buyers plan to use the home for a few weeks a year and rent it out the rest of the time. Queenstown has specific rules for this.
According to Queenstown Lakes District Council:
- Letting a home to paying guests for stays under 90 days is classed as Residential Visitor Accommodation, and you must register it with the council.
- Rates increase if you let it for more than 28 days a year, and rise further beyond 180 days.
- Operating outside the standards for your zone requires resource consent.
Check the zoning and rules for the specific property before you buy, especially if rental income is part of your plan. NZ lenders may also assess short-stay income differently from long-term rent.
Tax: get advice on both sides
Owning in NZ while living in Australia means dealing with two tax systems. Areas to discuss with an accountant who understands both countries include:
- Declaring NZ rental income in both countries, and how foreign tax offsets apply
- Whether interest on the Australian equity release is deductible
- Australian capital gains tax when you eventually sell, and NZ's bright-line rules if you sell within a short period
- Getting a New Zealand IRD number which you'll generally need before the property transfer can be registered. Your NZ lawyer can guide you through this process.
We don't give tax advice, but we can introduce you to accountants who work with trans-Tasman clients.

How Mortgages Plus helps
Buying property across the Tasman can mean coordinating finance in two countries.
I'm NZ-born and an Australian citizen, with strong networks in both Australia and New Zealand. For Australians buying property in New Zealand:
• We arrange the Australian finance, including releasing equity from your Australian property with a lender that suits your circumstances and plans.
• Our licensed New Zealand partner arranges the NZ mortgage, while we work together to coordinate the finance from pre-approval through to settlement.
• We can connect you with local professionals, including New Zealand lawyers, accountants and foreign exchange specialists.
The aim is to make the Australian and New Zealand sides of the purchase work together, rather than treating them as two completely separate transactions.
Thinking about buying in Queenstown? Book a call, and we can talk through the Australian finance, your available equity and how the NZ lending side could work.
Related reading:
- Buying Property in Australia as a New Zealander
Frequently asked questions
Can Australians buy property in Queenstown? Yes. Australian citizens are exempt from New Zealand's foreign buyer ban and can buy residential property without Overseas Investment Office consent. Australian permanent residents usually need consent unless they live in NZ.
How much deposit do Australians need to buy in New Zealand? Most NZ banks lend 60% to 70% to overseas borrowers, so expect to need a 30% to 40% deposit. Many Australians fund this by releasing equity from their Australian home.
Can I use equity in my Australian home to buy in Queenstown? Yes. An Australian lender can release equity from your Australian property to fund the deposit, and an NZ lender provides the mortgage on the Queenstown property. Lender policies vary, so structure matters.
Is there stamp duty in New Zealand? No. New Zealand doesn't charge stamp duty on property purchases, which reduces upfront costs compared with Australia.
Do Australians pay capital gains tax on NZ property? Australian tax residents are generally taxed in Australia on capital gains from overseas property, including property in New Zealand. NZ's bright-line rules may also apply if you sell within two years. Speak to an accountant about your situation.
Can I rent out my Queenstown holiday home on Airbnb? Potentially. Short-stay accommodation in Queenstown is subject to Queenstown Lakes District Council rules. Registration, council rates and consent requirements can vary depending on the property, its zoning and how often it is rented. Check the rules for the specific property before buying if short-stay income is part of your plan.
Can an Australian broker arrange an NZ mortgage? Australian brokers can't arrange NZ loans directly. At Mortgages Plus, we arrange the Australian finance and work alongside our licensed NZ partner, who arranges the NZ mortgage.
About the author
Chris Dodson is the founder and Principal Broker of Mortgages Plus. NZ-born and based in Manly, Sydney, Chris specialises in helping Australians and New Zealanders navigate property finance across the Tasman. Mortgages Plus arranges Australian lending and works alongside licensed New Zealand advisers, lawyers, accountants and other professionals to help clients coordinate cross-border property purchases.
Chris Dodson, trading as Mortgages Plus, is an authorised Credit Representative (No. 50855) of Australian Mortgage Advisors Group Pty Ltd, Australian Credit Licence (No. 388570).